Checkbook - Account Tracker

Screenshots
Details
- Rating
- 4.29K reviews
- Version
- 2.1.2
- Developer
- TinyWork Apps
Analysis by Norviv
I like finance apps that stay out of the way. When I open a checkbook register, I usually want one thing: a clear record of what has left my account, what is still pending, and how much money I can safely spend. Checkbook - Account Tracker takes that focused approach instead of trying to become a complete banking platform. It is a free finance app from TinyWork Apps, built around the familiar paper checkbook register and adapted for a phone.
That narrow purpose is both its appeal and its main limitation. In my experience, the app makes sense for someone who wants to manually track an account, especially when card transactions, cash spending, checks, or scheduled payments need to be recorded in one place. It is less suitable for anyone expecting automatic bank synchronization, investment tools, bill negotiation, or a polished all-in-one money dashboard.
The app has been available since July 24, 2015, and its current version is 2.1.2. That history matters because this is not a brand-new budgeting experiment; it is an established, modest tool with a very specific job. Its average rating is 3.6 from around 9,300 ratings, while its install count has passed 100,000. Those figures suggest a useful but not universally loved product, which matches my impression: the basic idea is practical, but the experience depends heavily on whether you enjoy keeping records yourself.
How the current checkbook experience works
I find the current experience easiest to judge as a personal ledger: I enter activity myself and use the running balance to keep pending spending in view, rather than expecting the app to connect to a bank. That approach can also help in a household, but I would first decide whose account the register represents and who is responsible for keeping it current. With that boundary clear, the next question is how to coordinate entries without treating one phone-based record as a shared banking system.
A manual register rather than a connected bank account
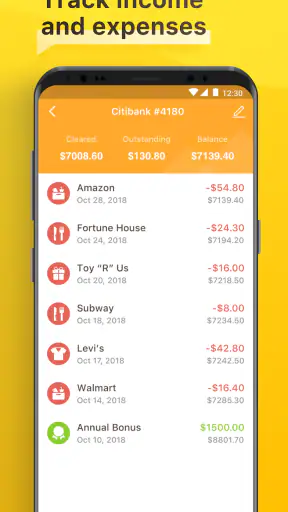
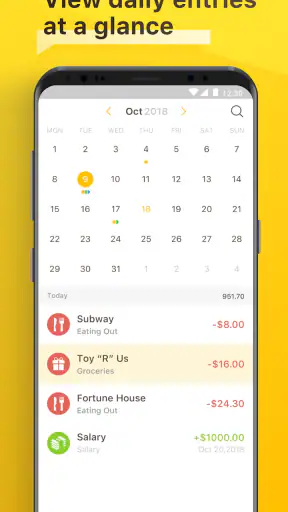
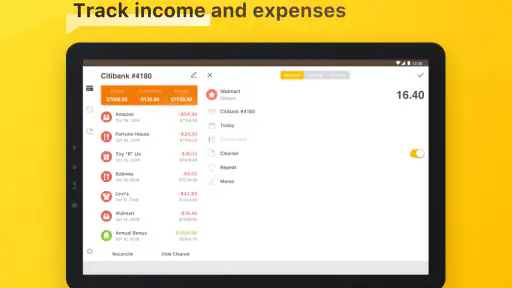
The central workflow is straightforward. I treat the app as a digital register: I enter a transaction, identify what it was for, and use the running balance as a second check against my actual account. This is particularly helpful when the balance shown by a bank does not reflect every payment I have mentally accounted for. A check that has not cleared, a cash purchase I might otherwise forget, or a card payment still waiting to post can all be kept visible in my own record.
The important distinction is that this kind of tracker depends on disciplined input. It is not a replacement for checking the bank’s official balance. Instead, it gives me a personal working balance that can include transactions before they appear in the bank account. That makes it valuable for planning, but only when I enter information promptly and accurately.
A realistic example is a weekend when I pay for groceries with a debit card, withdraw cash for a small purchase, and schedule a payment for the following week. I can record each item while the details are fresh, then look at the balance after accounting for all three. The bank may show only some of them immediately; the register gives me a more cautious view of what is really available.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Why the old-fashioned approach still has a place
Many modern finance apps try to reduce effort through automatic connections. That can be convenient, but it can also make people passive. With this app, I have to make a deliberate decision every time I record spending. For users who want to build awareness around purchases, that small pause can be a strength rather than an inconvenience.
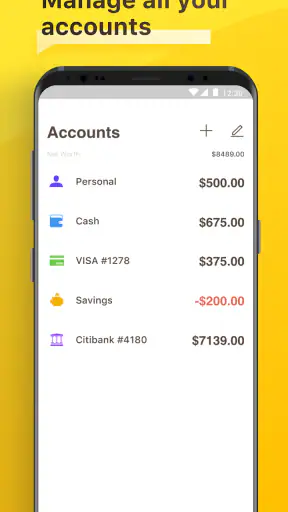
I also see a practical benefit for people who use more than one financial institution or who keep a separate cash account. A manual register does not need every account to support the same connection service. I can use the same basic habit for a checking account, a household cash reserve, or an account that I prefer not to connect to a third-party service.
There is a trade-off, though. The app cannot know that I bought something unless I tell it. If I forget several transactions, the running balance becomes misleading. I would not recommend relying on it as the sole source of truth for someone who rarely reviews spending or wants everything imported automatically.
Useful habits that make the register more reliable
The best way to use this app is to record transactions at the moment they happen, not at the end of the week. I find that a short entry made immediately is more dependable than trying to reconstruct several days of spending from memory. For card purchases, I would record the amount when the purchase is made, then compare it with the posted bank transaction later.
A second useful habit is to separate “available now” from “safe after pending items.” The register is most helpful when I include expenses that have been committed but have not cleared yet. That prevents a bank balance from creating a false sense of spare money. It also makes the app more than a simple history list: it becomes a personal forecast based on the transactions I know about.
A third tip is to reconcile regularly rather than waiting for a problem. When the bank statement or online balance is available, I compare recent entries and investigate differences immediately. A small mismatch is easier to explain than a large one created by weeks of missed purchases. This workflow is especially useful for people who still write checks, because uncleared checks can otherwise disappear from day-to-day thinking.
What the app is good at, and where it feels limited
Its strongest quality is focus. The app does not need me to learn a complicated budgeting system before I can start recording an expense. That makes it approachable for someone moving away from a paper register, a spreadsheet, or scattered notes. The familiar concept also reduces the learning curve: the question is simply what was spent, when it happened, and how it affects the balance.
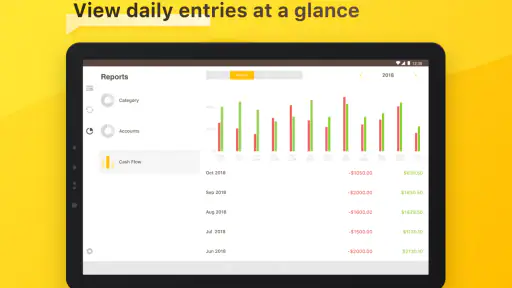
The limitation is that a register is not the same as a full financial plan. People who want detailed category analysis, long-term goals, automatic account feeds, shared household collaboration, or broad financial reports may find the experience too narrow. A dedicated budgeting service or a bank’s own app may be a better fit for those needs.
I would also be cautious about expecting frequent, dramatic changes. The current version is 2.1.2, and the product’s long availability points to a mature, focused utility rather than a rapidly expanding platform. That is not automatically negative. In fact, users who prefer a stable manual tool may appreciate the lack of unnecessary complexity. Still, anyone choosing it should do so for the register itself, not because they expect it to evolve into a different kind of finance product.
How it compares with paper, spreadsheets, and bank apps
Compared with a paper checkbook, the phone-based format is easier to carry and less likely to be left at home. I can make an entry when I am standing in a store or checking my account before a payment. The digital running balance is also more convenient than repeatedly doing arithmetic by hand. The drawback is that the experience depends on the phone and the app being available, while a paper register is completely independent of software.
Compared with a spreadsheet, this app is likely to feel faster for simple entries because it is designed around the register task rather than a blank grid. A spreadsheet can be more flexible, especially for custom reports and formulas, but that flexibility requires setup and maintenance. I would choose the app for quick personal tracking and a spreadsheet when I need a more elaborate record or analysis.
Compared with a bank app, the roles are different. The bank app is authoritative for posted transactions and account information. This tracker is useful for my own planned balance and for recording activity that may not have cleared. I would use both together, not treat one as a substitute for the other. That distinction is one of the most important things a new user should understand before relying on the register.
Who should use it every day
I think it is a good match for people who want a digital replacement for a paper checkbook, users who manually manage a single spending account, and anyone who wants a lightweight way to account for pending expenses. It can also suit users who are uncomfortable linking financial accounts and prefer entering transactions themselves.
It may be especially helpful for someone trying to stop overspending without adopting a complex envelope system. Recording each purchase makes spending visible, while the running balance keeps attention on the immediate consequence. That is a different kind of discipline from reviewing colorful charts after the fact.
On the other hand, I would skip it if automatic imports are essential, if several people need to edit the same household ledger, or if detailed financial reporting is the main goal. I would also avoid making it the only tool for business bookkeeping, tax records, or complicated account reconciliation. Its simplicity is useful, but it should not be mistaken for professional accounting software.
What existing users may notice about the product’s evolution
The release date and current version show a product that has had time to settle into its basic identity. From a user’s perspective, that means the sensible expectation is continuity around manual account tracking rather than a sudden transformation into an automated financial hub. I see the version history context as reassuring for someone who wants a familiar register, but less exciting for someone shopping for a constantly expanding money-management suite.
For existing users, the practical question is whether the current workflow still matches their needs. If the app already helps them maintain a clean running balance, a version number alone is not a reason to change habits. The more important test is whether entries remain easy to make and whether the register supports their personal reconciliation routine. A focused tool can remain useful for years when its core job is still the right job.
New users should approach the app with the same mindset. I would begin with one account and a small number of daily entries, then compare the result with the bank after a few days. That simple trial reveals more than a long feature checklist: it shows whether manual tracking fits the user’s routine and whether the app’s presentation is clear enough for regular use.
Cost, age rating, and the practical commitment
The app is free to install and carries an Everyone age rating, so the basic barrier to trying it is low. There are in-app purchases ranging from $0.99 to $19.99 per item. Because of that, I would pay attention to what is available without upgrading and decide whether any paid option genuinely improves the way I keep records. The right choice depends on how often I use the register and what level of convenience I need.
For a simple personal ledger, free access may be enough. If I were considering a purchase, I would first establish a consistent routine and confirm that the app fits my account-tracking habits. Paying for extras before solving the basic problem of entering transactions would not make much sense. The value comes primarily from maintaining an accurate record, not from installing the app alone.
Important expectations before moving from paper
The move from paper to a phone does not remove the need for reconciliation. I still need to check the official account, recognize pending charges, and correct mistakes. The app can make those tasks more convenient, but it cannot protect me from an incorrect amount or a forgotten entry. That is why I see it as an aid to financial awareness rather than an automatic safety net.
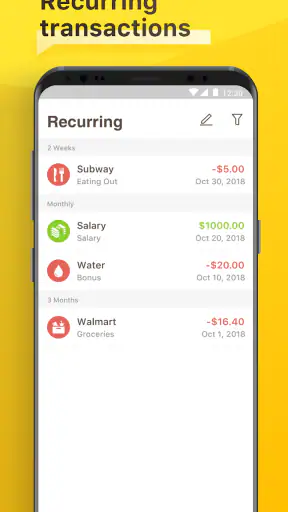
I would also decide in advance how to handle recurring payments. Even without turning the register into a full budget, I can use a consistent note or description for rent, subscriptions, utilities, and transfers. Consistency makes later review much easier. If every recurring expense is entered differently, the record becomes harder to scan and the app loses some of its practical value.
What I would watch before committing long term
If I planned to use this app for years, I would watch how well it continues to fit my changing finances. A simple register is excellent while my needs are limited, but a new job, shared expenses, multiple accounts, or more ambitious savings goals can expose its boundaries. At that point, I might keep the app for quick checking while moving broader planning to another tool.
I would also watch the balance between simplicity and maintenance. The product’s appeal depends on entering transactions without friction. If that process becomes cumbersome, the manual model stops being an advantage. Conversely, if the app stays easy to use and continues to provide a dependable register, its focused design remains a reasonable alternative to more complicated finance platforms.
My overall view is positive but specific: this is a practical account tracker for people who want control through manual recording. It is not trying to replace a bank, a complete budget planner, or accounting software, and I would not judge it by those standards. I would recommend it to a friend who misses the clarity of a paper checkbook but wants that record on a phone. Its real strength is turning everyday spending into an intentional habit, provided I do my part and keep the entries current.
For users who value automation, shared access, or deep analysis, another finance app will probably be a better long-term choice. For users who want a straightforward digital register, the free entry point, Everyone rating, and established presence make it worth trying. The decision comes down to one honest question: do I want an app that records my financial activity for me, or one that helps me record it myself? If the second answer sounds right, Checkbook - Account Tracker remains a sensible, focused option.
Frequently Asked Questions
01What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you record and monitor personal finances from your mobile device. You can enter income, expenses, deposits, withdrawals, transfers, and other transactions, then review your account balances and activity in one place. It is especially useful for people who want a simple alternative to complicated budgeting or banking applications.
02Can I use Checkbook - Account Tracker with multiple accounts?
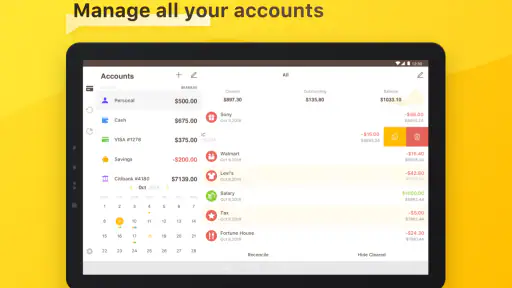
Yes, the app is intended to support tracking for more than one financial account, such as checking, savings, cash, credit, or other personal balances. Keeping accounts separate makes it easier to understand where your money is located and review transactions independently. Before downloading, check the current app version and settings because account limits and available organization features may vary.
03Does Checkbook - Account Tracker connect directly to my bank?
Checkbook - Account Tracker primarily focuses on manually recording and organizing transactions rather than replacing your bank’s official application. You should not assume that balances or transactions will automatically synchronize with your financial institution. Manual entry can provide greater control and privacy, but it also means you need to update the records regularly so the information remains accurate.
04Can I schedule recurring transactions and track future payments?
The app may be useful for recording regular transactions and planning upcoming financial activity, depending on the features available in the version you install. Recurring bills, salary payments, subscriptions, and transfers can be easier to monitor when entered consistently. However, users should verify whether automatic reminders, repeating entries, notifications, or forecasting tools are included on their device and operating system.
05Is Checkbook - Account Tracker safe for managing financial information?
Because the app can contain sensitive details about your spending and account balances, you should review its privacy policy, permissions, backup options, and available security settings before using it extensively. Avoid entering banking passwords, card PINs, or unnecessary personal information. Use a device lock, keep the application updated, and confirm whether data is stored locally, synchronized online, or shared with third parties.


